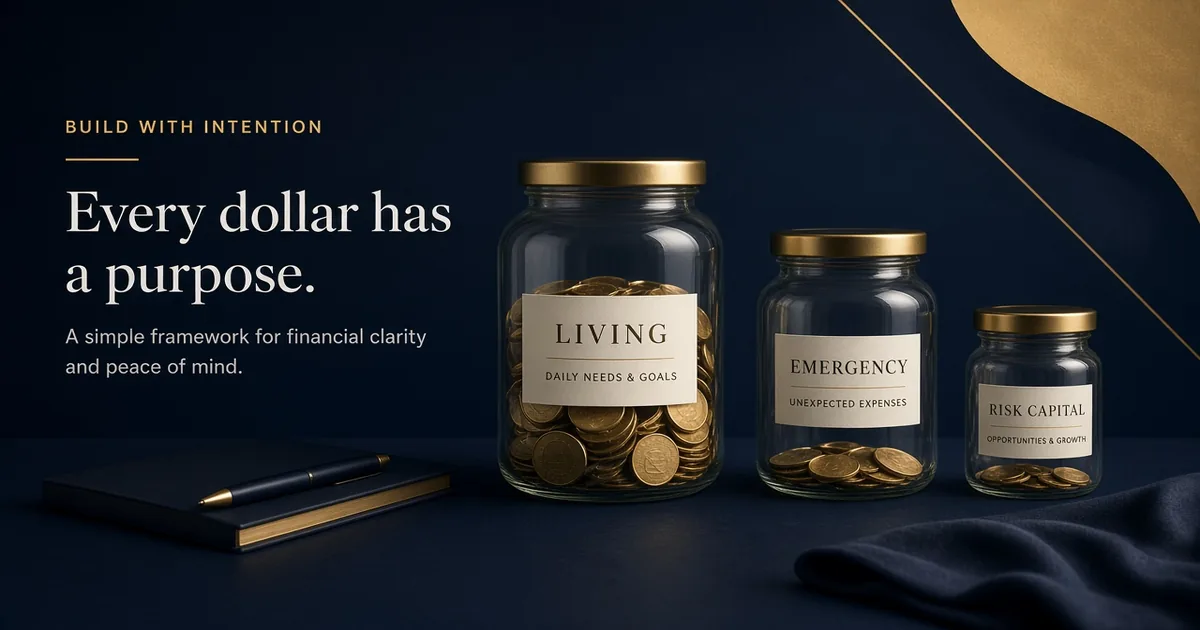
- Risk capital is money whose total loss would not break rent, food, debt minimums, insurance, or a true emergency reserve
- ‘Afford to lose’ is a household cash-flow and buffer test — not a personality trait or a motivational slogan
- Broker minimum deposits are technical thresholds, not recommended risk capital
- If losing the deposit would force borrowing, unpaid bills, or cancelled essentials, it is not risk capital
- Define a hard lifetime and monthly loss budget before any live funding; size the account down to that budget
Open a free Exness demo
- Practice with virtual funds before you deposit
- Start on a small account before you size up
- MT4, MT5 and the Exness app
- Spreads from 0.0 by account type
- 800K+ active clients
- Confirm the legal entity before you fund
- Withdrawals are requested in the client area; arrival time varies
- Fund a live account only after the demo is clear
- TL;DR — Risk Capital in One Screen
- Why “Afford to Lose” Is Not Motivational Fluff
- Short Answer
- Detailed Explanation
- Example
- Common Mistake
- Professional Tip
- A Clear Definition of Forex Risk Capital
- Short Answer
- Detailed Explanation
- Example
- Common Mistake
- Professional Tip
- The Total-Loss Test (Use Before Any Deposit)
- Short Answer
- Detailed Explanation
- Example
- Common Mistake
- Professional Tip
- Risk Capital vs Broker Minimum vs Position Size
- Short Answer
- Detailed Explanation
- Example
- Common Mistake
- Professional Tip
- Red Flags: This Is Not Risk Capital
- Short Answer
- Detailed Explanation
- Example
- Common Mistake
- Professional Tip
- How Risk Capital Links to Readiness and Disclosures
- Short Answer
- Detailed Explanation
- Example
- Common Mistake
- Professional Tip
- Checklist — Tag Money Before You Fund
- Glossary
- Key Takeaways
- Related Reading
Authoritative framing: Regulated CFD marketing repeatedly asks whether you can afford to take the high risk of losing your money — language embedded in ESMA-era retail CFD warnings and FCA retail CFD restrictions. The CFTC separately warns about forex fraud and pressure to fund accounts. This article turns “afford to lose” into a usable cash test for intending traders. Educational only — not personal financial advice.
Affiliate & risk disclosure: ForexTradeLab may earn commissions from regulated broker links elsewhere on the site. CFDs and forex can result in rapid loss of capital. See disclaimer and affiliate disclosure.
TL;DR — Risk Capital in One Screen#
| Bucket | Role in a forex decision |
|---|---|
| Living costs | Never fund speculative trades from money needed for essentials |
| Emergency reserve | Keep separate; not trading fuel |
| Risk capital | Only surplus that can hit zero without breaking the first two |
| Broker minimum | Technical door — not a recommended budget |
| Fail the test if… | Example |
|---|---|
| Loss forces borrowing | Credit card / payday loan to “reload” |
| Loss skips rent or food | Deposit equals next month’s housing buffer |
| Loss drains true emergency cash | “I’ll refill the medical fund after I win” |
Pair with: should I start forex — scorecard, risk-warning percentage explained, forex minimum capital, risk management.
Why “Afford to Lose” Is Not Motivational Fluff#
Short Answer
Because retail forex/CFDs are leveraged speculation where deposits can go to zero — and most measured retail accounts lose money.
Detailed Explanation
Every serious broker risk warning ends with a question about whether you can afford the high risk of losing your money. That sentence exists because supervisors documented chronic retail CFD losses and built product interventions around leverage, close-outs, and disclosures (ESMA summary).
The global FX market’s size — about $9.6 trillion average daily OTC turnover in the BIS 2025 Triennial Survey — does not make a $400 retail account “safe.” Liquidity and 24-hour access make it easy to keep clicking with the wrong money.
“Afford to lose” is therefore a funding filter, not a vibe. It decides whether you should open live risk at all this month.
Example
Two people both “have $1,000 free.” Person A has three months of expenses in a separate savings account and no high-interest debt. Person B’s $1,000 is the only cushion before rent day. Same nominal cash. Only Person A has candidate risk capital.
Common Mistake
Equating “I want this money to grow” with “I can afford to lose it.” Desire for growth is the opposite emotional state from acceptance of total loss.
Professional Tip
Say the sentence out loud: “This balance can go to zero and my life still works.” If you hesitate, shrink the number until the sentence is true — or stay on demo.
Key point: Risk capital is surplus cash tagged for speculative learning loss — not hope, not rent, not the emergency fund.
A Clear Definition of Forex Risk Capital#
Short Answer
Risk capital = cash beyond essentials and emergency reserves whose complete loss leaves your household solvent on a normal planning horizon.
Detailed Explanation
Use this working definition for ForexTradeLab readers:
Forex/CFD risk capital is money you have already emotionally and financially written off as a possible learning cost of speculative trading, held apart from:
- Money for housing, food, utilities, transport, insurance, and dependent care
- Minimum debt payments
- A genuine emergency reserve (job loss, medical, urgent family costs)
- Near-term known bills (tuition, tax, travel already committed)
It is not:
- Expected investment returns for retirement
- “Temporary” use of the rent float
- Borrowed funds
- Money you need back by a fixed date (holiday, school fees, medical procedure)
This definition matches how regulated warnings ask about affordability: they assume loss is plausible, not rare.
Example
Leila earns a stable salary, keeps six weeks of expenses in a high-access savings account, and has $500 left from a completed side project with no assigned bill. That $500 can be labelled risk capital. Her savings account cannot.
Common Mistake
Calling overtime pay “house money” and depositing it the night it clears. Unassigned income still fails the test if losing it would cancel next month’s buffer rebuild.
Professional Tip
Open a separate bank sub-account or envelope labelled FTL-RISK (or similar). Only that balance may move to a broker. Psychological separation reduces “just another $200 from main.”
The Total-Loss Test (Use Before Any Deposit)#
Short Answer
Assume the deposit hits zero tomorrow; check whether essentials and the emergency plan still hold.
Detailed Explanation
Run this sequence on paper:
- Write the candidate amount (e.g. $400).
- Subtract it from available cash in your mental model permanently.
- Confirm 3–6 months of essentials are still fundable from income + non-trading reserves.
- Confirm no debt is required to replace it.
- Confirm no fixed obligation needed that cash in under 90 days.
- Check body response — panic, secrecy from a partner, or “I’ll make it back” urgency are fail signals.
If any step fails, the candidate amount is too high. Cut it or wait.
Also apply a monthly loss budget: even inside risk capital, decide the maximum you will lose in 30 days before a mandatory pause. That pairs with when not to trade.
Example
Omar wants to deposit $2,000. After the total-loss test he realises $1,500 is earmarked for a visa fee in eight weeks. True risk capital tonight is $500. He deposits $300, not $2,000.
Common Mistake
Passing the test only for a “normal” 10% drawdown while refusing to imagine a 100% loss. Leveraged accounts can gap and stop out hard — see margin call vs stop out.
Professional Tip
Write a one-line stop rule: “If lifetime learning losses hit $X, I delete the apps for 90 days and return to education only.” Decide $X while calm.
Risk Capital vs Broker Minimum vs Position Size#
Short Answer
Three different numbers: what you may lose, what the broker accepts, and what each trade may risk.
Detailed Explanation
| Number | Meaning | Beginner error |
|---|---|---|
| Risk capital | Max money that may go to zero | Treating it as a profit target bankroll |
| Minimum deposit | Smallest funding the entity accepts | “Broker says $5 so $5 is enough edge” |
| Per-trade risk | Cash loss if stop hits (often ≤1% of equity) | Risking 10–20% to “make it worth it” |
A tiny account can still be wrong money if it was borrowed. A larger account can be right money if it is surplus and trades are sized from stop distance (position size guide, 1% risk rule).
For capital math context see forex minimum capital and tiny account cost floor.
Example
Risk capital = $600. Deposit = $300. Per-trade risk at 1% of $300 = $3. If the minimum lot makes a logical stop cost $12, either widen education on demo, choose a micro/cent structure if available and suitable, or accept that live trading should wait — do not abandon the $3 rule to force a trade.
Common Mistake
Depositing the entire risk capital on day one because “more margin feels safer.” Extra unused margin often becomes extra temptation to oversize.
Professional Tip
Fund ≤50% of tagged risk capital first. Keep the rest offline until a withdrawal test and two weeks of rule-following exist.
Red Flags: This Is Not Risk Capital#
Short Answer
If funding requires secrecy, debt, missed bills, or a comeback deadline, stop.
Detailed Explanation
Stop-funding list:
- Credit cards, buy-now-pay-later, or loans used to deposit
- Money from a joint household account without explicit agreement
- Cash meant for rent, school, medicine, or tax
- “Last chance” deposits after a revenge-loss spiral (emotional pitfalls)
- Deposits driven by a bonus countdown rather than a written plan
- Money you must double by a date to solve a life problem
The CFTC fraud advisory highlights pressure tactics and unrealistic return claims — both push people to fund with non-risk capital. Separately, romance/pig-butchering patterns are covered in our scam guide.
Example
After a bad week, Dana deposits the grocery budget because a signal group promised a “recovery trade.” That deposit fails every definition in this article.
Common Mistake
Believing negative balance protection or a regulated logo converts rent money into risk capital. Protections do not change household cash reality. See NBP explained.
Professional Tip
If you need a win to feel okay telling a partner what you deposited, the amount was already too large.
How Risk Capital Links to Readiness and Disclosures#
Short Answer
Right money + wrong readiness still fails; wrong money + perfect quiz still fails.
Detailed Explanation
Capital hygiene sits beside other gates:
- Readiness: Should I start scorecard
- Disclosure literacy: Risk warning percentage
- Onboarding integrity: Appropriateness test
- Process: How to start forex + demo journal
- Entity: Verify licence
Passing an appropriateness quiz does not enlarge risk capital. A low broker loss-percentage relative to a peer does not justify funding with borrowed cash.
Example
Jules scores 80/100 on the scorecard, passes the quiz, understands the 75% loss disclosure — and still waits because surplus cash this quarter is $0 after rebuilding an emergency reserve. Correct call.
Common Mistake
Using education progress as permission to raid the emergency fund (“I know enough now, so the money is safer”). Knowledge does not change loss mechanics.
Professional Tip
Review risk-capital status on payday and after any income shock — not only on signup day.
Checklist — Tag Money Before You Fund#
- Monthly essentials listed in your base currency
- Emergency reserve confirmed and ring-fenced
- Candidate amount passes the total-loss tomorrow test
- No debt funding
- Lifetime learning-loss cap written
- Monthly loss cap written
- First deposit ≤ portion of the lifetime cap
- Per-trade risk rule set (commonly ≤1% while learning)
- Partner/household agreement if money is shared
- Demo practice planned before live orders
- Bonus/timer pressure ignored
Glossary#
| Term | Meaning |
|---|---|
| Risk capital | Speculative funds that can be lost in full without breaking essentials or emergency reserves |
| Emergency reserve | Cash buffer for genuine non-trading shocks |
| Lifetime deposit | Smallest funding a broker entity accepts |
| Per-trade risk | Planned cash loss if the stop is hit as designed |
| Lifetime budget / learning-loss cap | Maximum total speculative loss you accept for a learning phase |
| Monthly loss cap | Maximum loss in 30 days before a mandatory pause |
| Surplus cash | Money left after essentials and emergency reserve |
| Revenge deposit | Funding driven by urge to recover prior losses |
Key Takeaways#
- “Afford to lose” is a household solvency test, not a slogan.
- Emergency funds and living costs are never forex risk capital.
- Broker minima and leverage options do not define what you should deposit.
- Assume total loss of the live balance before you fund.
- Right capital still needs readiness, entity checks, and a written risk process.
Related Reading#
- Should I start forex trading? Scorecard
- How to read broker risk warning percentages
- Forex broker appropriateness test explained
- Forex minimum capital — how much to start
- One-percent risk rule with examples
- Why most forex traders lose money
- First month of forex — what to expect
Next step: write your lifetime and monthly loss caps today. If surplus is zero, stay on education and demo via how to start forex. If you later fund a regulated account available in your country (for example XM where eligible), deposit only tagged risk capital and keep first-week size tiny. Eligibility depends on your country and the legal entity.
Risk warning: CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. A large share of retail investor accounts lose money when trading CFDs. Never deposit money you cannot afford to lose in full. This page is educational, not personal financial advice.
Comments
Add a useful note for other traders. We review comments before publishing.